On September 16, 2026, the Federal Reserve raised its benchmark rate by a quarter point, to a target range of 3.75% to 4%. Headlines about "rising rates" can make it sound like car loans just got a lot more expensive. For most used-car buyers, the Fed's move matters less than three things you control: your credit tier, where you get the loan, and how much you borrow.
- The Fed's hike was 0.25 percentage point. Average used-car APRs by credit tier range from 6.29% to 21.62% (Experian, Q2 2026). Your tier matters far more.
- Edmunds put the average used-car APR at 10.6% in Q3 2026, with an average of $30,703 financed over 70.4 months.
- Get preapproved with at least two or three lenders within about two weeks, then let the dealer try to beat your best offer in writing.
01What the Fed did, and why car buyers feel it
The FOMC's September 16 statement raised the federal funds target range "by 1/4 percentage point to 3-3/4 to 4 percent," on a 12–0 vote, saying that "inflation remains elevated." Auto loans don't move one-for-one with the federal funds rate. Lenders price them off their own funding costs and your risk. But the direction matters. Cox Automotive's chief economist, Jeremy Robb, said in October that interest rates are "climbing rapidly," and Cox lists rising rates as a reason used-vehicle values fell faster than usual this fall (Cox, Oct. 7).
So far, average rates have only edged up. Edmunds' Q3 2026 data shows the average used-car APR at 10.6%, compared with 10.5% in Q2 and 10.8% a year earlier. The average used-car payment was $582 on $30,703 financed. Most of Q3 came before the September hike, though, so it may show up more in Q4.
02Your credit tier matters most
Experian's Q2 2026 averages show how wide the range is:
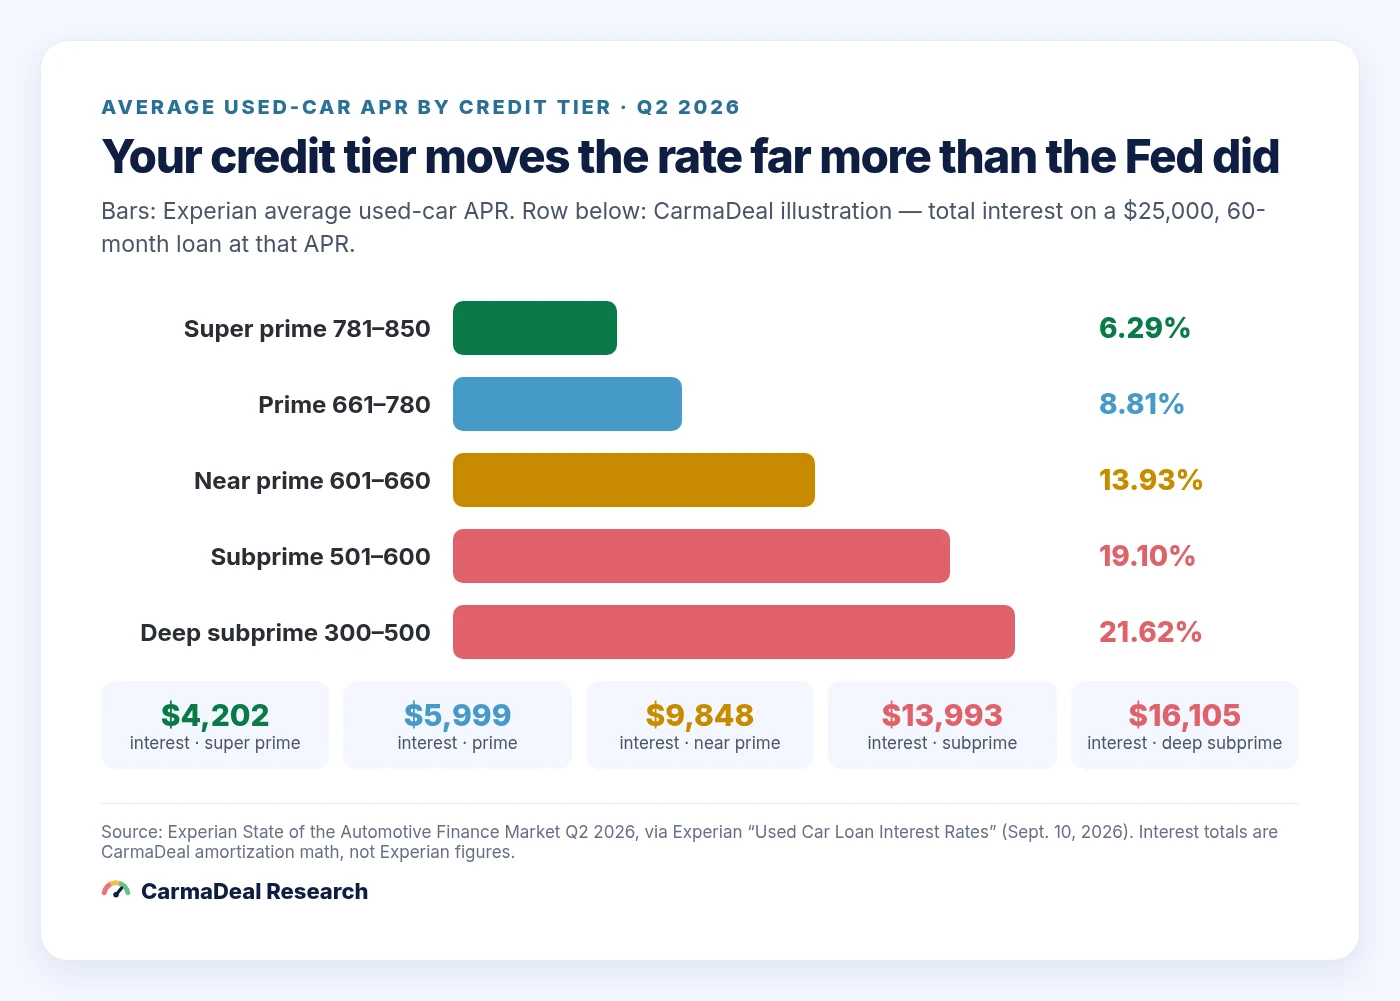
On the same $25,000, five-year loan, a super-prime borrower at 6.29% pays about $4,200 in interest. A subprime borrower at 19.10% pays about $14,000. The quarter-point Fed hike would add roughly $3 a month to a loan like that, while moving up one credit tier can save $30 to $70 a month. If your score is close to the line between tiers, paying down a credit card balance or fixing a reporting error before you apply can be worth more than any negotiation on the car.
03Get preapproved, then let the dealer compete
Experian explains that with dealer-arranged ("indirect") financing, the dealer typically sends your application to several lenders and presents one offer. That's convenient, but "could result in a higher interest rate due to dealer markups." A preapproval from your bank, a credit union, or an online lender gives you a real number to compare against.
- Apply with two or three lenders within a short window. Experian notes that submitting auto-loan applications within about two weeks minimizes the impact on your credit.
- Compare APR and term, not monthly payment. A lower payment over more months can cost more in total. See our guide to the 84-month loan trap.
- Tell the dealer you're preapproved, after you've agreed on price. Then ask: "Can you beat [X]% APR for [Y] months, in writing?" If they can, great. If not, use your own loan.
- Read the contract APR. Make sure the APR, term, and amount financed on the retail installment contract match what you agreed to, with no add-ons rolled in.
04Borrow less
The other lever is how much you finance. Every $1,000 you don't borrow at 10.6% for 72 months saves roughly $356 in interest (CarmaDeal amortization math). There are three main ways to borrow less:
- Pay a fair price. Negotiating $1,500 off a car you'd finance saves you the $1,500 plus the interest on it.
- Use your trade-in wisely. Get outside offers before you trade. If you owe more than the car is worth, read our negative-equity guide before you roll that balance into a new loan.
- Put more down. Edmunds shows the average used-car down payment slipped to $3,865 in Q3 2026 from $3,973 a year earlier. A bigger down payment lowers both the payment and the risk of owing more than the car is worth.
05Should you wait for rates to come back down?
Probably not, if you need a car now. The Fed's statement made no promise about future moves, and nobody can reliably time auto-loan rates. In dollar terms, a quarter point on a typical used-car loan is a few dollars a month. A few weeks of waiting can easily cost more than that if the car you want sells or prices move. Concentrate on the things you control: your credit, your preapprovals, and the price. If rates do fall later, a loan with no prepayment penalty lets you refinance or pay it down early. Ask the lender about that before you sign, and get the answer in writing.
06Settle the price before the rate
Settle the price before you talk about financing. Once you know the out-the-door number, you know how much you need to borrow, and every lender's offer can be compared on the same amount. Enter the car's 17-character VIN on CarmaDeal and add the advertised price to get a Deal Score from live local comparables and an itemized out-the-door estimate for your ZIP. That's the number to take to your lenders.
Sources and verification notes
- Federal Reserve, FOMC statement, Sept. 16, 2026.
- Edmunds, Q3 2026 auto finance data, Oct. 1, 2026 (used APR, payment, amount financed, term, down payment).
- Experian, The Latest Used Car Loan Interest Rates for 2026, Sept. 10, 2026 (Q2 2026 APR by tier; indirect financing; two-week rate-shopping window).
- Cox Automotive, September 2026 MUVVI trends (Robb quote).
- Interest totals and per-$1,000 savings are CarmaDeal amortization calculations. Your actual rate depends on lender, credit, term, and vehicle.